Buffett’s Investment in Coca-Cola
Dear investors,
On August 30, Warren Buffett turned 90. To celebrate the occasion, we decided to present an analysis of one of his most iconic investments: the purchase of a significant stake in Coca-Cola during the 1980s.
This is one of the cases we present in our training program for new members of our team: “If you went back in time and evaluated Coca-Cola in 1988, would you buy the stock?” In this letter, we will try to summarize the main insights we draw from this training.
We start with a quiz. A well-regarded business magazine once published the following statement:
“Several times every year a weighty and serious investor looks long and with profound respect at Coca-Cola’s record, but comes regretfully to the conclusion that he is looking too late.” – Fortune Magazine
In what year was this sentence published? The correct answer is in the footnote on the next page3:3:
- a) 1938
- b) 1944
- c) 1957
- d) 1968
- e) 1979
- f) 1986
Investment background
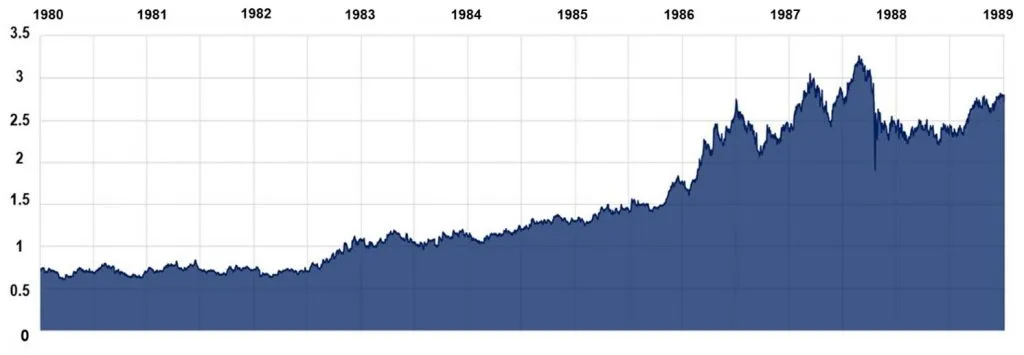
In 1988, Buffett began buying Coca-Cola shares. Many analysts were skeptical, since the stock had been rising for several years and was trading at the highest levels in its history (the share price had more than tripled over the decade, not counting dividends).
Chart 1 – Coca-Cola share price (1980-1988)
The stock looked expensive. It was trading at a price/earnings multiple1 of 15-19x at a time when long-term interest rates were 9% per year.
Even so, Buffett bought 7% of Coca-Cola’s shares, representing an investment of US$1.02 billion. It was a significant amount and represented 21% of Berkshire Hathaway’s net worth2 at the time!
1 P/E (Price/Earnings) is a multiple widely used in the financial markets. It measures a company’s market value relative to its annual net income. As a rule, the higher the multiple, the more “expensive” the company tends to be.
2 Berkshire Hathaway is Buffett’s investment holding company.
3 The quote was published in 1938.
What Buffett saw in the company
In his 1988 annual letter, Buffett commented on his investment in Coca-Cola for the first time:
“In 1988 we made major purchases of (…) Coca-Cola. We expect to hold these securities for a long time. In fact, when we own portions of outstanding businesses with outstanding managements, our favorite holding period is forever. We are just the opposite of those who hurry to sell and book profits when companies perform well but who tenaciously hang on to businesses that disappoint. Peter Lynch aptly likens such behavior to cutting the flowers and watering the weeds.
We continue to concentrate our investments in a very few companies that we try to understand well. There are only a handful of businesses about which we have strong long-term convictions. Therefore, when we find such a business, we want to participate in a meaningful way. We agree with Mae West: “Too much of a good thing can be wonderful.” – Warren Buffett, Berkshire Hathaway’s 1988 Letter
In 1989, he also praised the work that CEO Roberto Goizueta was doing to return the company to a growth path after a period of stagnation during the 1970s.
Based on statements made by Buffett and Munger at the time and subsequently, we understand that he based his investment decision on three main factors:
Potential for growth in consumption per capita
In 1988, Coca-Cola was already a strong brand throughout the world: it was the global leader, with 45% of the global market share in soft drinks, and it operated in more than 160 countries. In 1990, average global Coca-Cola consumption was already 43 cans per person per year. With such an already strong presence, how would the company grow?
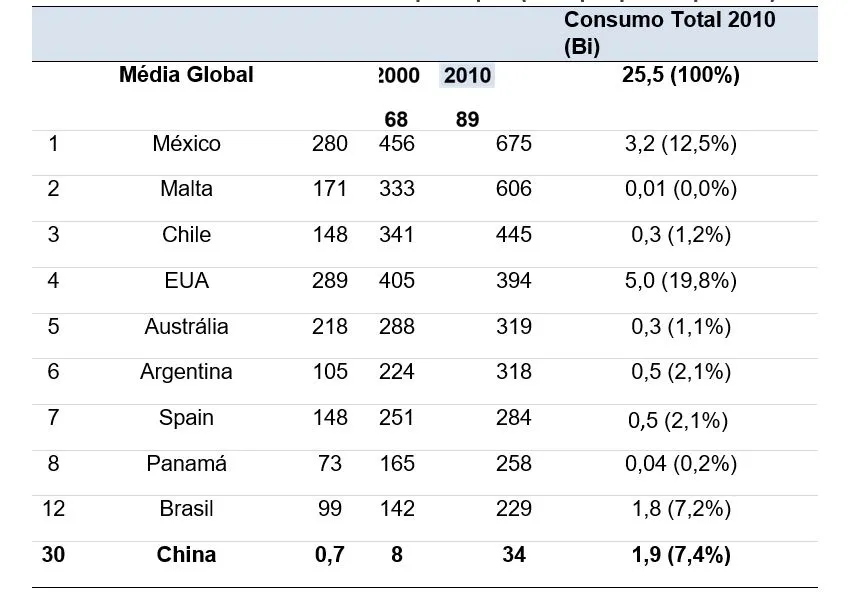
Despite this strong presence, brand penetration varied greatly from country to country. As shown in the chart below, while average consumption in the US was 289 cans per capita in 1990 (almost 7 times the global average), in China this figure was a meager 0.7.
There was clearly a lot of room for growth. Even with consumption already very high in the US and limited growth potential there (in fact, consumption fell between 2000 and 2010), there was plenty of room to increase volumes abroad.
China, in particular, had very low penetration and presented an enormous growth opportunity given its population of 1.3 billion people. Indeed, per capita consumption grew 49-fold between 1990 and 2010, and today China is one of Coca-Cola’s main markets.
Chart 2 – Per capita Coca-Cola consumption (cans per person per year)
Pricing power
One of the characteristics that make Coca-Cola a great business is its ability to consistently raise prices above inflation. Coca-Cola has a brand-loyal customer base and a relatively inexpensive product, which allows the company to raise prices constantly without weighing on consumers’ pockets. Today, for example, a 350 ml can of Coca-Cola costs around R$2.50. If the company raised the price to R$2.70 (an 8% increase, twice the annual inflation rate), few people would stop consuming the product.
In addition to providing protection in inflationary environments, pricing power also enables growth and margin gains, as the company’s revenue grows faster than its costs.
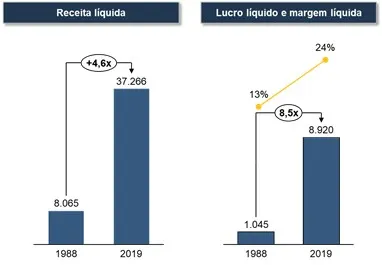
Evidence of this is the fact that, between 1988 and 2019, Coca-Cola’s revenue grew 4.6-fold, while the company’s net income grew 8.5-fold (net margin rose from 13% to 24%).
Chart 3 – Growth in Coca-Cola’s revenue and net income (in US$ million)
New investments with high returns
As mentioned in our previous letter, in addition to growing, a company needs good returns in order to truly create value for shareholders. In this respect, Coca-Cola had excellent results. The company’s average ROE[1] in the 1980s (before Buffett’s investment) was 25% per year and showed an upward trend that continued throughout the 1990s.
But why is this important?
The importance of a high ROE is that the company was able to grow without committing much of its capital or having to take on debt. In fact, the soft drink business requires little capital; the main investment the company makes every year is in marketing, investments that strengthen the brand and increase the company’s competitive advantages. This characteristic allowed Coca-Cola to grow both before and after Buffett’s investment while paying generous dividends to its shareholders – historically, the company has paid out 75-80% of the earnings it generates to shareholders in the form of dividends or share buybacks.
The result
In the first 10 years of Buffett’s investment in Coca-Cola, the stock performed spectacularly, delivering a return of 14 times the capital invested, equivalent to an annual gain of 30% per year (assuming reinvestment of dividends).
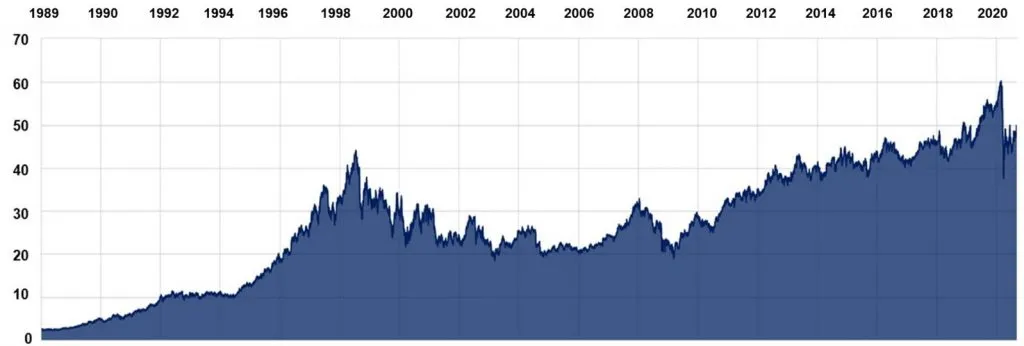
However, with the change in management following the death of CEO Roberto Goizueta in 1997 and, more recently, with healthy eating trends, the company’s stock has not performed as well as it used to. Even so, from the end of 1988 to August 2020, Coca-Cola’s stock appreciated 36-fold, which represented annual growth of 12% per year, assuming reinvestment of dividends. Considering the initial US$1.30 billion[2] that Buffett invested in the company in 1988, Coca-Cola has delivered a profit of almost US$30.0 billion to the investor over the last 30 years.
Chart 4 – Coca-Cola share price, not adjusted for dividends (1989-2020)
A recurring question is why Buffett did not sell his shares when the company reached a peak in 1998 and looked expensive at the time. There are three main reasons:
The first is the capital gains taxes Buffett would have paid had he sold the company’s shares. Given the stock’s enormous appreciation, the taxes paid would have been almost US$2.5 billion. Note: This tax concern exists because the investment in Coca-Cola was made through Berkshire Hathaway, which is a company subject to capital gains taxes. The situation is different for equity investment funds, which are taxed only when the unitholder requests a redemption (the fund can buy and sell shares without having to pay taxes).
Another reason is that the investment was very large. Buffett’s stake in Coca-Cola was valued at US$13.4 billion in 1998, which made the task of finding new investments as good as Coca-Cola quite challenging.
In addition to the previous points, Coca-Cola has always been an excellent dividend payer. Since at least 1988, Coca-Cola has paid quarterly dividends, increasing them every year. This characteristic has allowed Buffett to receive US$8.4 billion in dividends from Coca-Cola alone. Currently, his position yields US$656 million a year.
Even with a lower return over the last 20 years, Coca-Cola generated a profit of US$16.1 billion for Berkshire Hathaway between 1998 and 2019 (US$8.7 billion from share price appreciation and US$7.3 billion in dividends) – a profit greater than the US$13.4 billion invested in the company in 1998, which highlights the importance of a long-term focus.
Buffett still considers Coca-Cola a “great business,” but he admits that criticism of sugary soft drinks poses threats to the company.
The company has been expanding into other beverage categories (such as coffees, teas and juices) to keep growing, but these categories do not generate the same high margins as its main product. Even so, Coca-Cola is still a giant and has the best beverage distribution system in the world, which should help the company expand into these new product categories.
1 ROE (Return on Equity) is calculated by dividing a company’s net income by its shareholders’ equity. ROE is a measure of the company’s financial performance, as it indicates how well the company uses its resources to generate profit for shareholders. The higher the profit for a given amount of shareholders’ equity, the higher the company’s ROE.
2 Berkshire Hathaway invested US$1.024 billion in 1988-89 and added US$0.275 billion to the investment in 1994, for a total investment of US$1.299 billion. Buffett has never sold a single share of Coca-Cola.