Investment Case: Unipar Carbocloro
Dear investors,
We have had a few months of very turbulent markets. Given the period of uncertainty and anxiety, we dedicated our recent letters to topics more appropriate for that moment, such as investing in times of crisis and the historical returns of stocks vs. fixed income in several countries (including Brazil). For those who have not yet read them, all of these letters are published on our website.
This month, we decided to share our investment case in Unipar Carbocloro.
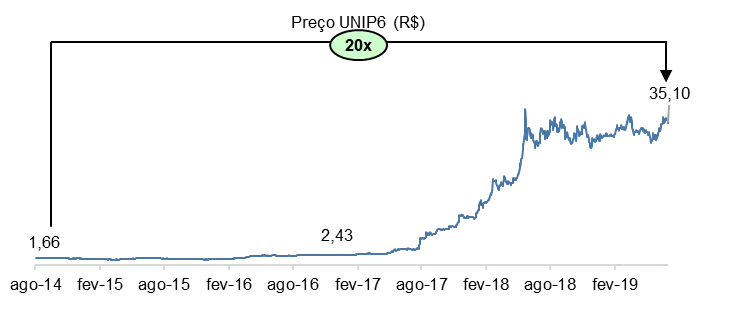
Unipar was Arcádia’s largest position in the 2015-19 period and was our first 20-bagger (it delivered a return equal to 20 times the capital invested!), as detailed in the chart below.
Chart 1 – UNIP6 historical return1
Below, we detail our investment process in the company, from identifying the opportunity through the decision to buy and, more recently, the decision to sell. We no longer hold the company in the fund.
Founded in 1969, Unipar Carbocloro is a company dedicated to the petrochemical segment. Today, the company focuses on three segments: chlorine, caustic soda (it is the largest producer in Latin America) and PVC (the second-largest producer).
For the few who remember their high school chemistry classes, Unipar’s production process is clear. The company uses salt (NaCl), water (H2O) and electricity as its main raw materials, and transforms them into chlorine (Cl2) and caustic soda (NaOH).
Chlorine has a wide range of industrial applications, including the production of PVC (used to manufacture plumbing pipes), water and sewage treatment, agricultural pesticides, and pulp and paper, among others. Chlorine can also be used to produce explosives, which gives the product two characteristics that make Unipar’s business attractive: (1) because of the risk of explosion, chlorine cannot be transported over long distances, and (2) because of this application, a company needs a multitude of licenses to be authorized to produce chlorine (and, consequently, caustic soda) – significant barriers to entry.
These characteristics give the industry the features of a natural monopoly and make the business highly profitable. Unipar has plants in the cities of Santo André (SP) and Cubatão (SP), which allows it to serve the South and Southeast regions, where the country’s largest consumers are located.
Since caustic soda and chlorine are normally produced together, the caustic soda market also has the same barriers to entry. The main difference is that, because caustic soda is not explosive, it can be transported over long distances; the company therefore also faces global competition, and the prices charged by Unipar follow those of the global market.
The focus on these 3 segments is something recent for the company. Historically, the company operated as a holding company with stakes in companies engaged in various activities in the petrochemical sector, and it even held a stake in a wind turbine blade company (Tecsis), which is currently under judicial reorganization. The chart below illustrates the tangled corporate structure that made up Unipar in 2006:
Chart 2 – Unipar’s organizational structure in 2006
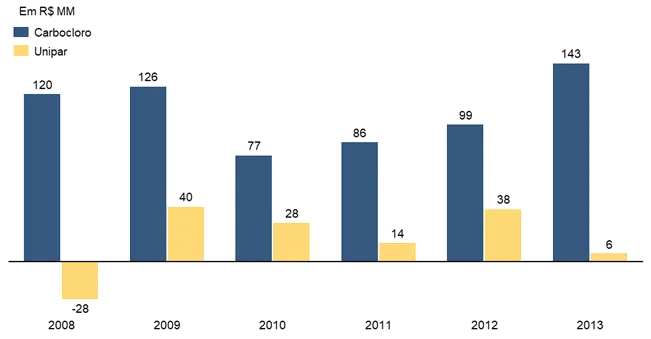
Between 2006 and 2010, a series of transactions took place aimed at simplifying the company’s corporate structure and focusing on the most profitable business (Carbocloro). The transactions were: the sale of Petroflex (2007); the sale of União Terminais (sold to Grupo Ultra in 2008); and the sale of Quattor (the company that held Unipar’s stakes in Petroquímica União, Rio Polímeros and Polietilenos União), Polibutenos and Unipar Comercial (sold to Braskem in 2010).
The complex history of corporate restructurings made the analysis difficult and made the company potentially misunderstood by the market.
In 2013, Unipar acquired the remaining 50% of Carbocloro (until then, its stake had been 50%) and became a company whose only asset was Carbocloro – a structure similar to the one that exists today.2
This transaction caught our attention because the terms of the deal were strikingly out of line with Unipar’s own market value: Unipar’s main asset at that time was its 50% stake in Carbocloro, and the offer to buy the remaining 50% was 20-30% higher than Unipar’s value on the stock exchange! Since the two halves of the same asset should obviously have the same value, the offer made it clear that Unipar’s executives believed their operations were significantly undervalued by the market.
We then decided to deepen our analysis.
It made little sense to evaluate the financial history of the Unipar holding company, since it included several operations that were sold during the restructurings; the accounting results therefore did not reflect the business’s future prospects. As shown in the chart below, an analysis that captured only Unipar’s results (and not Carbocloro’s) would be ineffective in assessing the company.
Chart 3 – Historical normalized net income (Unipar x Carbocloro)
The important thing was to analyze Carbocloro. Since Unipar disclosed little information about Carbocloro, we looked for its operating and financial history in alternative sources, such as balance sheets published in the Official Gazette. We even retrieved information going back to the 1980s!
The findings were very encouraging, as they showed characteristics typical of good businesses: stable volumes, high margins and high cash conversion, typical of businesses with few competitors and high barriers to entry.
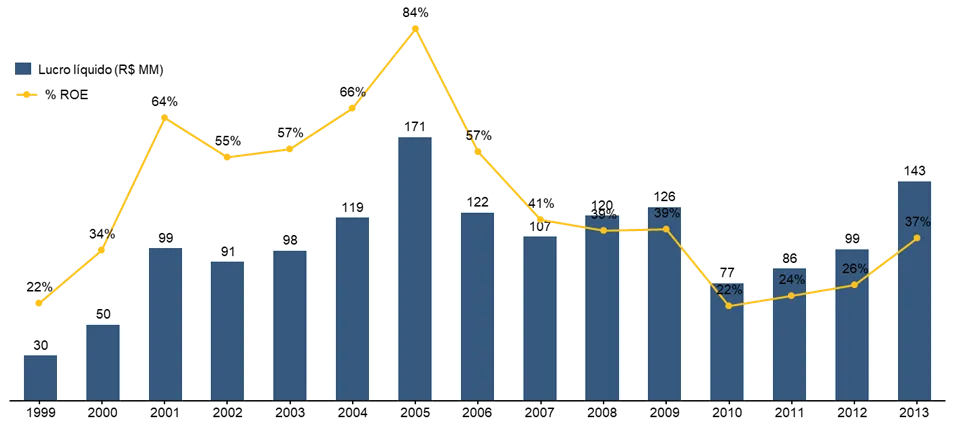
The chart below shows Carbocloro’s net income and return on equity (ROE) at the time of the analysis. Note that the company had never recorded a loss-making year, even in the worst crises, such as in 2002-2003.
Chart 4 – Carbocloro’s historical net income and ROE
A negative point for the company was its lack of growth: the company’s net income had not grown significantly since 2001. We understood that two factors were weighing on the company: (1) the industry’s idle capacity was close to historical highs, closely linked to the onset of the crisis we had under the Dilma government; (2) caustic soda prices were low in the international market which, combined with a depreciated dollar, contributed to lower-than-“normal” earnings. This conclusion was, in a way, reassuring, since even during a downturn in the cycle, the company remained profitable and cash-generative.
As for valuation, our estimates at the time were that, under conservative scenarios, the company looked very undervalued. Based on its level of cash generation, we estimated that the company should be worth at least twice its market value – even with the CDI at the time hovering around 12% per year!
After weighing everything up, we decided to invest, starting our purchases in late 2014.
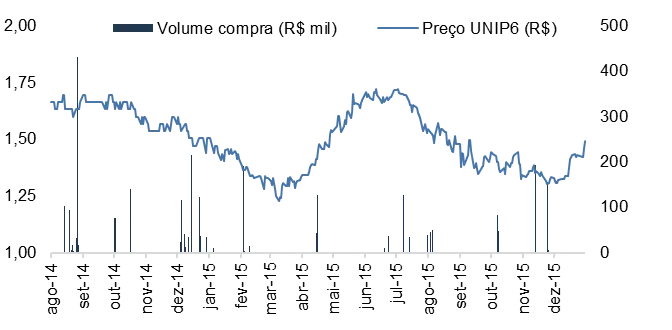
Despite the high return the stock delivered, we had to be very patient and disciplined. This is because we started buying in Aug/14 and, in just over 6 months, the shares had fallen by about 25% (compared with a 12% decline in the Ibovespa over the period)! Without a doubt, a far from encouraging start for the position.
A decline of this magnitude warranted a detailed review of the investment to assess whether we had made a mistake or whether there had been significant changes in the company or in the market that justified such a fall in value.
We found that, in fact, the company’s operating results were even better than our expectations, so the decline in the shares appeared to be driven solely by the market’s fear that macro factors could contaminate the company’s results (the timing coincided with the peak of the crisis that culminated in the impeachment in 2016).
We concluded that the decline did not seem reasonable, and we took the opportunity to keep buying at an even lower price. We built the position over a period of 18 months, during which the price remained attractive, as shown in the chart below.
Chart 5 – UNIP6 share price3 compared with purchase volume
During this same period, the company’s controlling shareholder, aware of the share’s discounted price, made a tender offer to take the company private at R$1.79/share4 (a 15% premium to the price at the time). Fortunately, we were able to coordinate with other minority shareholders and veto the offer at this price.
From 2016 onward, the stock began to deliver good returns. Three factors contributed to the improvement in results and, consequently, in the share price.
The first was the company’s own performance: benefiting from the rise in the dollar, it generated almost R$500 million in cash over a 3-year period (2014-16) – an amount greater than its market value at the time of our investment, and higher than we had estimated for the period. This cash generation was used to reduce net debt (which fell from R$580 million to R$188 million over the period), and the remainder was paid out to shareholders in the form of dividends.
The second factor was a move by the company in 2016 to acquire Solvay Indupa, a competitor operating in Brazil and Argentina with a presence in the caustic soda, chlorine and PVC segments. Solvay Indupa had been up for sale for a few years and, taking advantage of the lack of buyers (a sale to Braskem in 2014 had been blocked by the antitrust authorities), Unipar was able to acquire the asset at a good price. After a well-executed turnaround, Indupa became a cash-generating unit and enabled a considerable expansion in Unipar’s results.
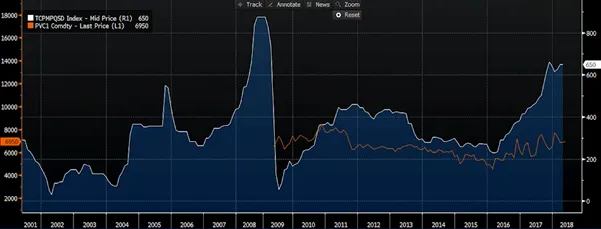
The third factor that influenced Unipar’s results was the rise in the price of caustic soda in the international market, as can be seen in the chart below. This increase was largely due to environmental issues, which banned the production of chlorine and caustic soda using an old technology and forced several plants around the world to halt production. Europe was the first region to impose this restriction, in 2017, which eliminated a significant portion of global supply and drove up the price of the commodity. Other factors also contributed, such as growing demand from China and the fact that chlorine and caustic soda plants in the US were already operating close to their production capacity limits.
Chart 6 – Historical caustic soda price (white line)
It is important to note that Unipar itself will have to replace its mercury plant in the coming years, which will require a significant investment.
As a result of these factors, between 2015 and 2018 the company increased its net income 6-fold and the stock appreciated 20-fold. In early 2019, given how much the stock had appreciated and how much the price of caustic soda had also risen, we decided to sell our Unipar shares in order to invest in other businesses with greater upside potential.
We still follow the stock closely, waiting for the day when a new opportunity to buy at attractive prices arises.
1 UNIP6 prices shown in the charts are adjusted for dividends and stock splits
2 To be exhaustive, there were two other transactions not mentioned. The first was the acquisition of a 25.25% stake in Tecsis (a wind turbine blade manufacturer) in 2011, and the second was the purchase of Indupa in 2016 (detailed in the text)
3 UNIP6 prices shown in the charts are adjusted for dividends and stock splits
4 The original tender offer price was R$4.40/UNIP6 share; the price presented in the text has been adjusted for dividends and stock splits